
What is approval of the financial statements for?
It is the official record of the general meeting (a meeting of all shareholders of an s.r.o. or a.s.), in which the previous year’s profit or loss is approved and a decision is made on what to do with that result. Shareholders may cover a loss or leave it uncovered in the company. They may distribute a profit, use it to cover losses from previous years or leave it undistributed in the company. Undistributed profit may remain in the company as retained earnings from previous years, or shareholders may transfer it to funds. The amount available for distribution is last year’s profit plus accumulated retained earnings from previous years, less uncovered losses from previous years.
This record must be in writing, signed by all shareholders and completed by 30.6.2021. If shareholders decide to distribute profit (to shareholders, managing directors or employees – if the articles of association allow it), they must pay it out within 3 months of the decision, i.e. no later than 30.9.2021. We must also remember the 15 % withholding tax payable on profit distributed in this way.
What must this record contain?
It must have a heading stating that it is the minutes of an ordinary general meeting and the date on which the meeting took place. It must also include information about the company (name, business identification number, registered office, file reference) and its shareholders (first name and surname, home address, date of birth, size of shareholding). The general meeting record for a company with a sole shareholder will of course differ from that for an s.r.o. with several shareholders.
For multiple shareholders, the internet offers plenty of templates you can use. A sole shareholder’s decision is a simpler record, which might look like this:
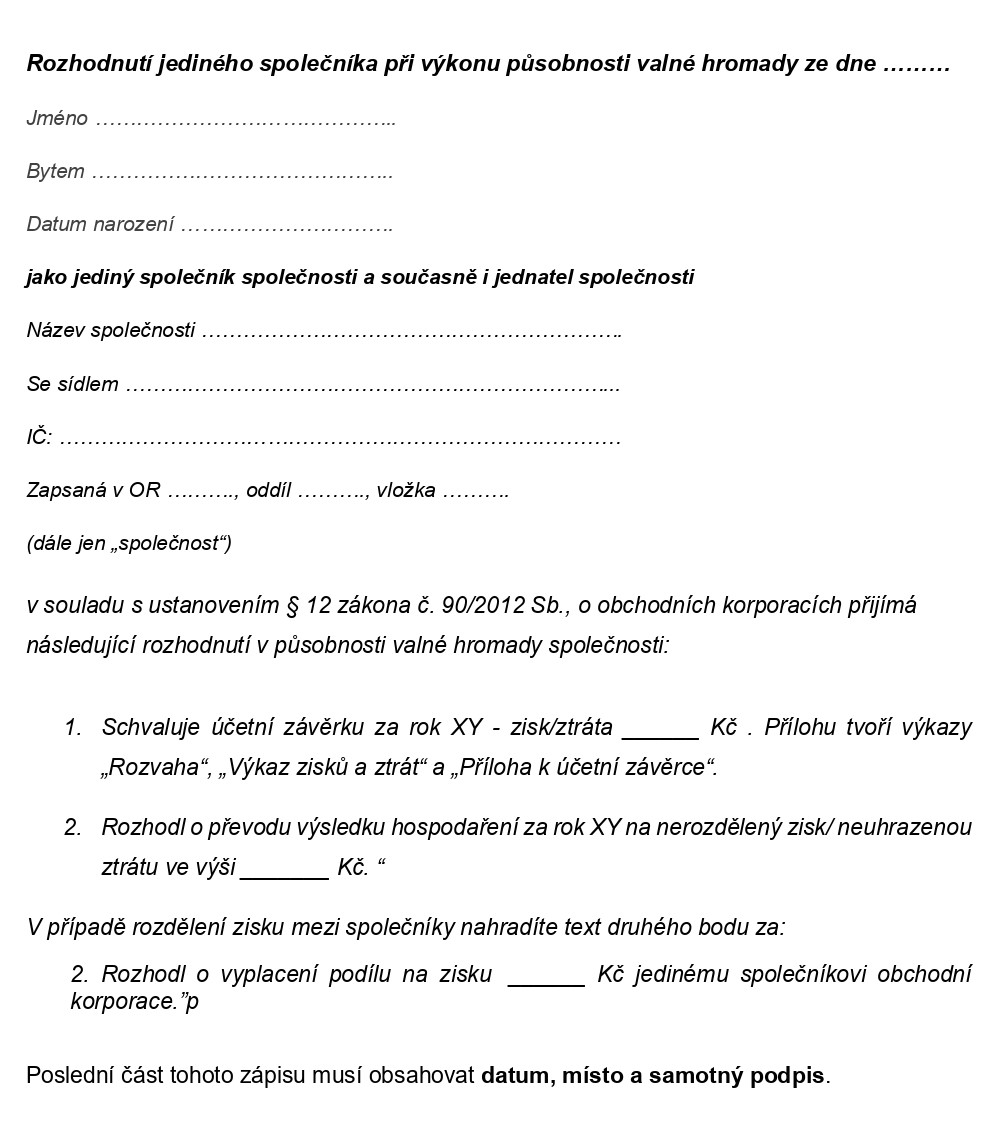
The approval of the financial statements is not sent anywhere; it remains among the company’s internal documents. If the shareholders do not convene a general meeting or draw up this document, the accountant automatically transfers the profit to retained earnings from previous years (or the loss to uncovered losses from previous years). However, it is a mandatory part of the financial statements and brings the previous year to a final, definitive close. 🙂
If you are unsure about the record, contact a lawyer: preparing notarial records and similar documents is not an accountant’s job. If you are unsure, feel free to get in touch and we will look at it together. 🙂